Contribute to 1.8% Annual Growth in Gallium Nitride (GaN) and Silicon Carbide (SiC) Power Semiconductor Markets
The Business Research Company’s Gallium Nitride (GaN) and Silicon Carbide (SiC) Power Semiconductor Global Market

Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

The Business Research Company’s Gallium Nitride (GaN) and Silicon Carbide (SiC) Power Semiconductor Global Market Report 2026 – Market And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 16, 2026 /EINPresswire.com/ — “The gallium nitride (GaN) and silicon carbide (SiC) power semiconductor market is rapidly gaining traction as industries prioritize energy efficiency and advanced power solutions. This sector is being shaped by evolving demands in electric vehicles, renewable energy, and sophisticated power electronics, which are driving technological innovation and expanding market opportunities. Let’s explore the current market size, key growth drivers, product segments, regional dynamics, and the leading players shaping this vibrant industry.
Market Size and Growth Outlook for the Gallium Nitride (GaN) and Silicon Carbide (SiC) Power Semiconductor Market
The market for GaN and SiC power semiconductors is projected to surpass $6 billion by 2030, representing roughly 1% of the broader Semiconductor and Related Devices market, which is expected to reach about $950 billion by the same year. When considering the entire Electrical and Electronics sector, anticipated to hit $5,579 billion by 2030, this segment accounts for close to 0.1%. The market is forecasted to grow at a strong compound annual growth rate (CAGR) of 25% through 2030, underscoring its expanding influence in the semiconductor landscape.
Request A Free Sample Of The Gallium Nitride (GaN) And Silicon Carbide (SiC) Power Semiconductor Market Report
https://thebusinessresearchcompany.com/sample_request?id=70609511&type=smp&name=GaN%20And%20SiC%20Power%20Semiconductor%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Key Factors Propelling Growth in the GaN and SiC Power Semiconductor Market
The push toward energy efficiency stands out as a primary growth engine for this market. GaN and SiC devices are favored because they minimize power loss during conversion and switching, can operate at higher voltages and temperatures, and are well-suited for use in data centers, industrial equipment, and consumer electronics. As electricity costs rise and regulations on sustainability tighten, adoption rates are accelerating. This factor alone is expected to contribute about 1.8% annual growth.
Another significant driver is the increasing popularity of electric vehicles (EVs). GaN and SiC semiconductors improve powertrain efficiency by enabling faster switching speeds, reducing energy loss, and enhancing thermal management. Silicon carbide, in particular, contributes to better battery range and quicker charging times. The global move toward vehicle electrification, supported by government incentives and infrastructure development, is projected to add roughly 1.6% yearly growth to the market.
Access The Detailed Gallium Nitride (GaN) And Silicon Carbide (SiC) Power Semiconductor Market Report Here
https://thebusinessresearchcompany.com/report/GaN-and-SiC-power-semiconductor-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Expanding applications in renewable energy and power electronics also bolster market growth. Efficient power devices are critical for solar inverters, wind turbines, and energy storage systems. GaN and SiC materials offer superior efficiency, compact designs, and greater reliability compared to traditional materials. Rising investments in renewable energy, grid upgrades, and smart energy systems are expected to drive approximately 1.3% annual growth in this sector.
The Emergence of Bidirectional GaN Power ICs Enhancing Market Capabilities
Innovations such as integrated GaN-based bidirectional power ICs are marking a new chapter for the GaN and SiC power semiconductor market. These devices improve conversion efficiency, allow for smaller system designs, and support high-frequency operations, making them ideal for EVs, renewable installations, and data centers. An example is Navitas Semiconductor Corporation’s April 2025 release of 650 V Bi-directional GaNFast power ICs designed for EV on-board chargers, solar inverters, and motor drives. Their chip combines GaN power switches with gate drivers, enabling bidirectional power flow with increased power density, reduced energy loss, and enhanced thermal performance.
Product Segmentation Highlights Dominance of Discrete SiC Components
The market divides into four main product categories: SiC power modules, GaN power modules, discrete SiC, and discrete GaN components. Among these, discrete SiC is expected to hold the largest share by 2030, accounting for 37% of the market or roughly $2 billion. This segment’s strength comes from its use in high-reliability industrial motor drives, high-voltage power conversion for heavy equipment and railway traction, and electronics designed for harsh environments. Demand for compact and efficient switching solutions suitable for next-generation energy management in industry and infrastructure further supports this segment’s growth.
Further segmentation of the GaN and SiC power semiconductor market includes applications such as power supplies, industrial motor drives, hybrid and electric vehicles, photovoltaic inverters, traction systems, and other specialized uses. Distribution channels break down into direct and indirect sales pathways.
Regional Market Leadership in the GaN and SiC Power Semiconductor Industry
Asia-Pacific is projected to dominate the GaN and SiC power semiconductor market by 2030, reaching $2.6 billion, up sharply from $0.9 billion in 2025, reflecting a 25% CAGR. This rapid expansion is driven by increased manufacturing of electric vehicles and charging infrastructure, broader adoption of high-efficiency power electronics in consumer and industrial sectors, growth in solar and wind power installations, expansion of data centers and 5G networks, energy-efficient industrial automation, and significant semiconductor manufacturing investments in countries like China, Japan, South Korea, and Taiwan.
China, in particular, is expected to lead nationally with a market size of $1.5 billion in 2030, rising from $0.5 billion in 2025 at the same 25% CAGR. This growth is fueled by expanding domestic semiconductor capacity, deployment of wide-bandgap devices in high-voltage industrial power systems, electrification of high-speed rail, smart grid projects, new energy storage solutions, ultra-fast charging infrastructure, aerospace and defense electronics, and government initiatives aimed at semiconductor self-sufficiency and electronics localization.
Combined Growth Across All Four Key Product Segments
The segments of SiC power modules, GaN power modules, discrete SiC, and discrete GaN are all poised to contribute substantially to market expansion, collectively adding more than $4 billion by 2030. Each category is expected to grow by about $1 billion between 2025 and 2030. This growth is driven by next-generation electric mobility powertrains, ultra-fast industrial charging stations, high-density power conversion applications, aerospace and satellite power technologies, high-frequency defense radar and secure communications, miniaturized energy conversion systems, and innovations in packaging and thermal management. These developments highlight a strong industry focus on power efficiency, system energy density, and high-performance electrification across mobility, industrial, and defense sectors.
Market Concentration Reflects High Entry Barriers in GaN and SiC Semiconductors
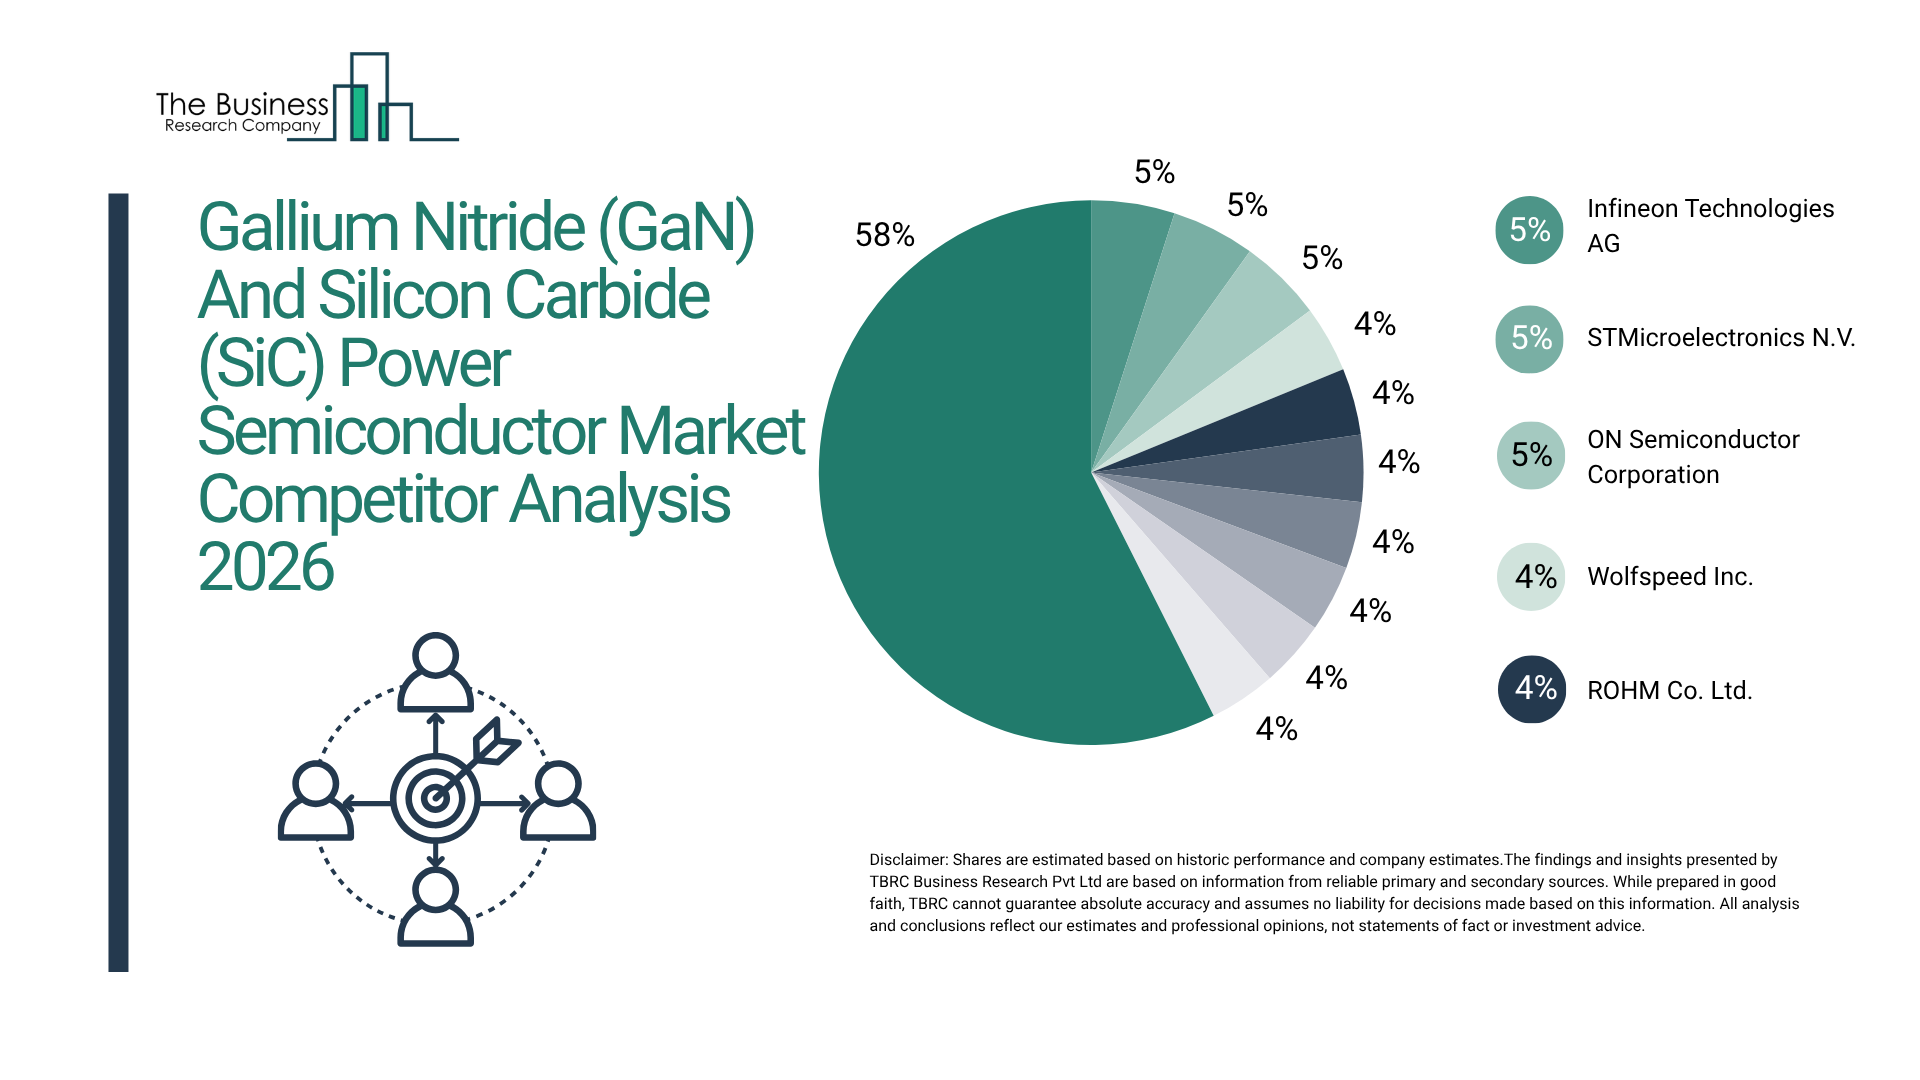
The GaN and SiC power semiconductor market remains highly concentrated, with the top 10 companies generating 42% of total revenue in 2024. This concentration reflects the demanding technological and capital requirements, such as advanced wafer fabrication, complex wide-bandgap material engineering, rigorous reliability standards, and the critical need for efficient power conversion in EVs, renewable energy, and industrial applications. Leading firms maintain their dominance through diversified wide-bandgap product portfolios, strategic OEM and Tier-1 partnerships, global fabrication and supply chains, and ongoing innovation. As demand grows for energy-efficient power conversion, vehicle electrification, renewable integration, and compact power electronics, collaborations, capacity expansions, and technological progress will continue to reinforce their market positions.
Market Share Breakdown of Leading Companies in 2024
The following companies held significant shares of the market in 2024:
– Infineon Technologies AG — 5%
– STMicroelectronics N.V. — 5%
– ON Semiconductor Corporation — 5%
– Wolfspeed Inc. — 4%
– ROHM Co. Ltd. — 4%
– Innoscience Technology — 4%
– Navitas Semiconductor Corporation — 4%
– Texas Instruments Incorporated — 4%
– Renesas Electronics Corporation — 4%
– NXP Semiconductors N.V. — 4%
How Industry Leaders are Maintaining Their Competitive Edge
To stay at the forefront, companies are focusing on advancing GaN and SiC material engineering to boost efficiency and handle higher voltages. They are leveraging wide-bandgap semiconductor architectures to improve power density and switching speeds while expanding wafer production capacity to reinforce supply chains and encourage broader commercial adoption. Integrating power electronics design to enhance device reliability and thermal management is also a key strategic priority.
Top Players Steering the GaN and SiC Power Semiconductor Market
Infineon Technologies AG led global sales in 2024 with a 5% market share, according to The Business Research Company. Their power semiconductor division offers a wide range of wide-bandgap devices, including GaN and SiC transistors, diodes, and modules tailored for electric vehicles, renewable energy systems, industrial drives, and efficient power conversion.
Other major industry participants include STMicroelectronics N.V., ON Semiconductor Corporation, Wolfspeed Inc., ROHM Co. Ltd., Innoscience Technology, Navitas Semiconductor Corporation, Texas Instruments Incorporated, Renesas Electronics Corporation, NXP Semiconductors N.V., Qorvo Inc., Mitsubishi Electric Corporation, Panasonic Holdings Corporation, Microchip Technology Incorporated, Alpha & Omega Semiconductor Limited, Fuji Electric Systems Co. Ltd., Efficient Power Conversion Corporation, SweGaN AB, Toshiba Electronic Devices & Storage Corporation, Littelfuse Inc., VisIC Technologies Ltd., Semikron Danfoss, Sanan IC, and Sanken Electric Co. Ltd.
Overview of the Supply Chain in the GaN and SiC Power Semiconductor Market
Key suppliers of raw materials essential to the GaN and SiC power semiconductor market include Wolfspeed Inc., Infineon Technologies AG, ON Semiconductor Corporation, STMicroelectronics N.V., ROHM Co. Ltd., Mitsubishi Electric Corporation, Toshiba Corporation, Sumitomo Electric Industries Ltd., Kyocera Corporation, Fuji Electric Co. Ltd., Hitachi Ltd., Renesas Electronics Corporation, Denso Corporation, Showa Denko K.K., Tokuyama Corporation, Nippon Steel Corporation, Saint-Gobain S.A., Corning Incorporated, 3M Company, DuPont de Nemours Inc., BASF SE, Dow Inc., Heraeus Holding GmbH, Norstel AB, and GT Advanced Technologies Inc.
On the distribution side, leading wholesalers and distributors include Arrow Electronics Inc., Avnet Inc., Digi-Key Electronics, Mouser Electronics Inc., Future Electronics Inc., RS Components Limited, TTI Inc., Allied Electronics and Automation, Ingram Micro Inc., Tech Data Corporation, Synnex Corporation, ScanSource Inc., Westcon Group, ALSO Holding AG, Esprinet S.p.A., Redington Limited, Exclusive Networks SA, EET Group A/S, Macnica Inc., ASBIS Enterprises PLC, Mindware FZ LLC, Logicom Public Limited, Bechtle AG, CDW Corporation, and Insight Enterprises Inc.
Prominent end users span industries and include Tesla Inc., Toyota Motor Corporation, General Electric Company, Siemens AG, Schneider Electric SE, ABB Ltd., Huawei Technologies Co. Ltd., Apple Inc., Samsung Electronics Co. Ltd., Dell Technologies Inc., Hewlett Packard Enterprise Company, Cisco Systems Inc., NVIDIA Corporation, Intel Corporation, AMD Advanced Micro Devices Inc., Qualcomm Incorporated, Panasonic Corporation, Sony Group Corporation, LG Electronics Inc., Ericsson AB, Nokia Corporation, Lockheed Martin Corporation, and Boeing Company.
Expanded capabilities in our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel-based forecasting dashboards
• Market hotspots infographics
• Key technologies and future trend analysis
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company“
Oliver Guirdham
The Business Research Company
+44 7882 955267
info@tbrc.info
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery

